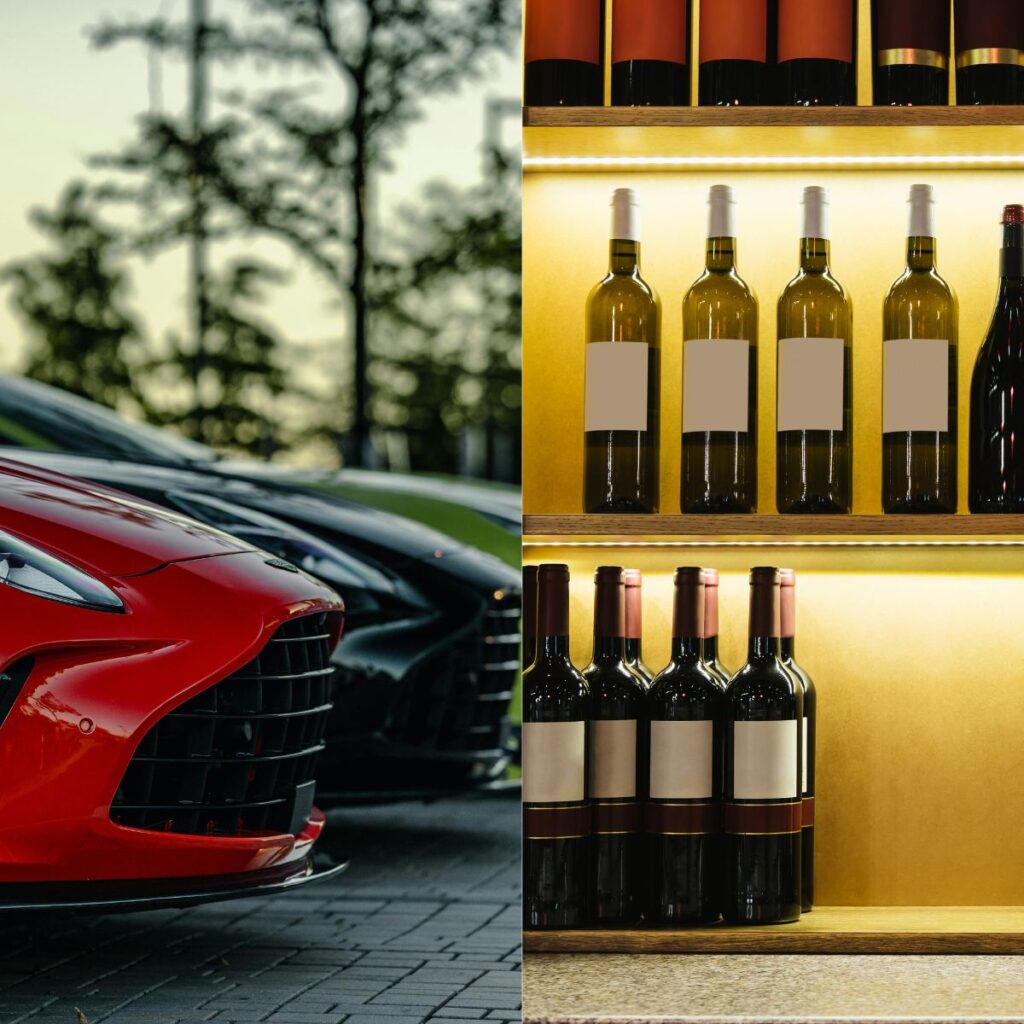
A collection is not the same thing as a pile of expensive belongings. A wine cellar built over a decade holds value a standard policy was never designed to recognize. So does a garage of cars chosen and restored with real intention. Most collectors find this out during a claim. That’s the worst possible time to find it out.
The Coverage Gap Most Collectors Don’t Know They Have
A standard homeowner’s or auto policy pays actual cash value. That means what an item is worth today, after depreciation, not what it cost you to acquire and not what it would cost to replace. For a car, that means blue-book value for the make and model. Nothing accounts for a matching-numbers engine, a documented ownership history, or three years of restoration work.
Wine works differently, but the shortfall is the same. Actual cash value treats each bottle in isolation. A cellar built as a provenance-documented collection is worth more than the sum of its individual bottles. A standard policy has no mechanism to recognize that difference.
That’s not a difference in what you own. It’s a difference in what your policy is designed to pay for.
Homeowner’s policies compound the problem with what insurers call “special limits of liability.” These are sub-limits that cap payouts on jewelry, silverware, and furs, regardless of what you paid, as the III’s overview of homeowner’s personal property coverage explains. Cars and wine typically aren’t even named in those special limits. They fall under your general personal property cap instead. One significant loss could exceed everything the policy was ever going to pay for the entire collection.
What Counts as a “Collection” for Insurance Purposes
Cars, wine, and memorabilia are the collector categories least likely to carry the right coverage. They don’t fit the “valuables” box most people picture when they think about scheduling property. Jewelry, fine art, watches, and coins are more commonly recognized as needing specialty treatment. Meslee has covered what real coverage looks like for a coin collection and for watches as an investment asset elsewhere on this blog. Much of that guidance applies here too.
Cars and wine still ask something different of a policy. A car collection combines three exposures at once: security (theft, vandalism), use (is it driven, shown, or stored?), and a valuation that shifts every time the market for a given model moves. A wine collection combines an environmental exposure, temperature and humidity control, with a valuation that usually moves the opposite direction of a car’s. Most wine appreciates with age, right up until it doesn’t.
Memorabilia sits somewhere between the two. Game-worn jerseys, signed items, and race-used parts carry an authentication burden neither cars nor wine face on their own: the piece is only worth its appraised value if the provenance behind it holds up, which means documentation matters even more here than it does for the rest of the collection.
Actual Cash Value vs. Agreed Value — In Plain Terms
Actual cash value pays what an item is worth today, after depreciation. The Insurance Information Institute’s explanation of how insurance settlements are calculated puts it plainly: an actual cash value policy pays the amount needed to replace an item, minus depreciation. For a fifteen-year-old car or a bottle purchased a decade ago, that number can land far below what you paid. It can also land far below what the market would charge to replace it today.
Agreed value works differently. You and your insurer agree on a value for the item, in writing, before a loss happens. That figure is typically backed by an appraisal, a bill of sale, or both. If a covered loss occurs, that’s the number the policy pays. No depreciation deduction. No negotiation over what “today’s value” means. No argument during a claim about whether a matching-numbers engine or a documented provenance chain should move the number.
For a collection with real value behind it, agreed value is coverage that fits what you own.
What an Appraisal Actually Needs to Show, and How Often
An appraisal for insurance purposes needs to establish more than a dollar figure. It needs documentation an insurer can rely on if a claim happens years later: condition at the time of appraisal, provenance or ownership history, clear photographs, and the appraiser’s credentials. A number with no documentation behind it is a starting point for a dispute. It is not a settled value. For a car, that means an appraiser who specializes in the model, not a general auto appraiser working from a standard guide. For wine, it means someone who can speak to provenance and storage history, not just label and vintage.
How often that number needs revisiting depends on the asset, not the calendar. Institutional risk managers face the same underlying problem collectors do: assets whose value doesn’t move on a simple depreciation curve. RIMS’ guidance on property valuation is consistent on the core point. Valuations go stale faster than people expect. An outdated number is one of the most common reasons a payout falls short of what a loss costs. A collection you haven’t had reappraised in five years is very likely insured at a number the market has already moved past.
For Car Collections
If a car is stored or under restoration with a third party, ask whether that shop carries garage-keepers liability. That’s coverage that protects your car while it’s in someone else’s care, custody, and control. Confirm it before the car leaves your garage, not after something happens to it there. An agreed-value auto policy should also account for exhibition and transport exposure if you show the car or have it moved by a third-party transporter. A car in transit carries a different risk profile than a car parked at home.
For Wine Collections
Two loss scenarios dominate wine claims: temperature-control failure and breakage. A cooling system that fails over a long weekend can damage an entire cellar before anyone notices. A homeowner’s policy’s scheduled property rider is usually built around jewelry and art. It’s not built around a cellar that depends on mechanical equipment running correctly around the clock, and it often won’t address that failure mode at all. Mysterious disappearance is coverage for loss you can’t otherwise explain. It matters more for wine than for almost any other collectible, and it’s worth confirming explicitly rather than assuming it’s included.
The Gap Between Purchase and Policy
There’s a stretch of time every collector runs through without thinking about it. It starts the moment you win an auction lot, or a dealer ships a bottle from out of state. It ends the moment you add the piece to your policy. During that window, the seller no longer has it, and your policy doesn’t cover it yet. A bottle in transit from an out-of-state dealer, or a car en route from an auction house, sits in exactly that window.
A seller’s own coverage, when one exists, usually stops at the loading dock or at handoff to a common carrier. It doesn’t follow the piece all the way to your door. If something happens in between, you own a loss nobody insured.
Meslee and Cabrella are sister companies. If you’re actively buying or shipping pieces for your collection, ask your advisor about coverage for the item while it’s in transit. Get it in place before the piece reaches your door, not after.
What Specialty Coverage Still Won’t Cover
Agreed value coverage is not a hedge against the market. It won’t protect you if the value of a car or a vintage you own simply falls. It also won’t cover ordinary wear: a chip in the paint from daily driving, a cork that dries out because a bottle sat somewhere other than its cellar. Specialty coverage protects against loss. It doesn’t protect against owning a collection whose value moves, up or down, with the market.
Talk to a Meslee Advisor Before You Add to the Collection
A collection built over years deserves a policy built with the same care. If your cars or wine haven’t been appraised recently, start there. If you’re not sure whether your current coverage would pay what the collection is worth, that’s worth confirming too. Your advisor works for you, not the carrier, which is exactly who you want in your corner when a car or a cellar represents years of decisions instead of a single purchase.
Contact our team at meslee.com to talk about agreed-value and scheduled coverage for your collection, before your next acquisition, not after a loss forces the question.